Bancassurance incentive management starts with who gets credit.
October 8, 2026
Puneet Gupta
Puneet Gupta
Key Insights
When I speak with bancassurance heads, the conversation often starts with targets and ends with credit. A policy is sold at a branch. The branch staff opened the conversation, the bank's insurance specialist completed the paperwork, and the insurer's relationship manager supported the sale. All three expect recognition, and they are paid by two different employers.
That question has become more pressing. On 23 September 2026, IRDAI released a consultation paper that proposes prohibiting volume-linked incentives for bank and NBFC staff selling insurance, tagging every policy to the person who sold it, and clawing back commission where mis-selling is established.
Bancassurance incentive management starts with who gets credit for each policy. Write the credit rule for every role, record it on the policy at the time of sale, and agree how renewal and cancellation data flows back from the insurer. Banks carry real weight here: they brought more than 49% of private life insurers' individual new business premium in FY2025.
A question worth asking the head of bancassurance this week: for a policy sold in September, could you name every person who was paid incentive on it?
When I speak with bancassurance heads, the conversation often starts with targets and ends with credit. A policy is sold at a branch. The branch staff opened the conversation, the bank's insurance specialist completed the paperwork, and the insurer's relationship manager supported the sale. All three expect recognition, and they are paid by two different employers.
That question has become more pressing. On 23 September 2026, IRDAI released a consultation paper that proposes prohibiting volume-linked incentives for bank and NBFC staff selling insurance, tagging every policy to the person who sold it, and clawing back commission where mis-selling is established.
Bancassurance incentive management starts with who gets credit for each policy. Write the credit rule for every role, record it on the policy at the time of sale, and agree how renewal and cancellation data flows back from the insurer. Banks carry real weight here: they brought more than 49% of private life insurers' individual new business premium in FY2025.
A question worth asking the head of bancassurance this week: for a policy sold in September, could you name every person who was paid incentive on it?
Table Of Content
How much of India's life insurance moves through banks
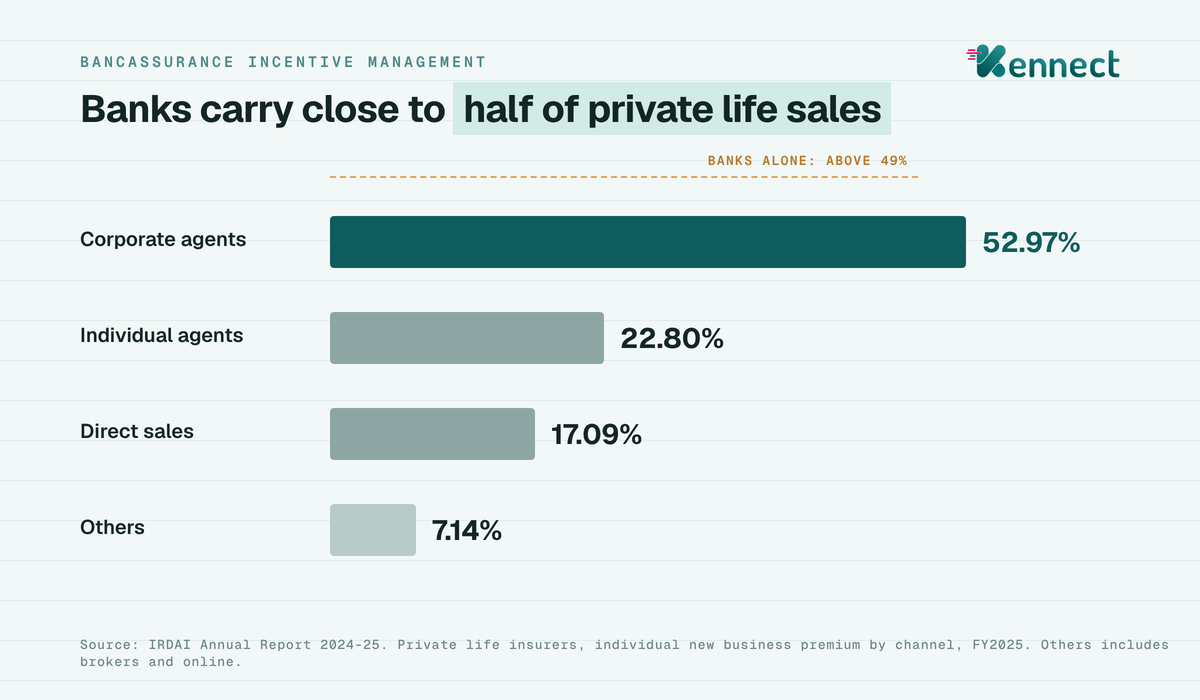
Banks carry close to half of private life insurers' new business in India. According to the IRDAI Annual Report 2024-25, corporate agents brought 52.97% of private life insurers' individual new business premium in FY2025, and banks alone contributed more than 49%. Individual agents brought 22.80% and direct sales 17.09%.
Source: IRDAI Annual Report 2024-25, individual new business premium by channel, FY2025, as reported by Outlook Money and Insurance Business Asia
Under the IRDAI (Registration of Corporate Agents) Regulations 2015, as amended in 2022, a bank acting as a corporate agent can tie up with up to three insurers each in life, general and health insurance. Many branches therefore sell policies from several insurers, through staff who also sell deposits, loans and cards.
For a private life insurer, the bank branch is the main point of sale, and the people at that branch are paid by the bank.
A prohibition on volume-linked or reward-linked incentives for bank and NBFC staff who sell insurance.
A central identity mechanism that onboards each salesperson and tags every policy to the person who sold it.
Commission clawback where mis-selling is established, with the salesperson's record published through the registry.
Lower commission caps for large distribution entities, including a reported first-year cap of 20% on life policies with premium terms of ten years or more.
A prohibition on compulsory bundling of insurance with loans and other financial products.
These are proposals, and the final rules may change after consultation. The direction is clear enough to plan for.
Read the consultation paper itself before redesigning any scheme, and take legal advice on how the final rules apply to your bank and insurer contracts.
IRDAI's proposals move bank staff incentives away from volume and tie every policy to a named seller.
Who gets credit for a bancassurance policy
One policy sold at a branch can involve three or more people.
Branch staff who hold the customer relationship and open the conversation.
The bank's insurance specialist or desk, who completes the needs analysis and the paperwork.
The insurer's bancassurance or relationship manager, who trains branch staff, supports the sale and services the policy.
The branch or cluster manager, who may carry an insurance target for the branch.
Each of them is paid by a different employer on a different plan. The bank pays its staff. The insurer pays its relationship manager. The commission flows from insurer to bank as the corporate agent.
When the policy-level seller tag arrives, each of these credits will need to agree with one record. The principles that govern split sales compensation apply here: decide the shares before the sale, and write them down.
Private life insurers' individual new business premium by channel, FY2025. Source: IRDAI Annual Report 2024-25
One bancassurance policy carries credit for staff on two payrolls, and the policy tag will expect those credits to agree.
What a bank staff incentive can read instead of volume
If the final rules prohibit volume-linked incentives for bank staff, an incentive still has to recognize good selling. The measures below read the quality of a sale. Each one depends on how the final rules define what is permitted, so treat this as a planning list.
Quality measures a bank staff incentive could read, and the record each needs
Measure
What it shows
The record it needs
Persistency at 13 months
The policy suited the customer well enough to stay in force
Renewal status from the insurer, tagged to the seller
Free-look cancellations
Policies returned in the free-look period
Cancellation records with the reason, tagged to the seller
Suitability record completed
A needs analysis was done and documented
The suitability form linked to the policy
Complaints and grievances
Sales that led to a complaint or a mis-selling finding
Grievance records from the insurer and the bank
Training and certification
The seller is certified for the products sold
Certification records against the seller identity
None of these measures can be read without the policy tagged to the person who sold it, and without data from the insurer flowing back to the bank.
A quality-based incentive reads what happened after the sale, which means the bank needs the insurer's policy data tied to each seller.
Where bancassurance incentives leak today
Three gaps are visible in many bancassurance programs.
The seller is not recorded on the policy
Branch staff, specialists and relationship managers all touch the sale, and the policy carries one code, often the branch. Incentives are then allocated by branch target or by manager judgment. When a dispute or complaint arrives, nobody can show who sold the policy.
Commission is paid on policies that later cancel
A policy that cancels in the free-look period or lapses early has already earned a payout for someone. Without a clawback rule that reaches each person who was paid, the recovery falls on the bank's commission alone.
Liability is shared and records are not
In August 2026, a district consumer commission in Hyderabad held a bank and an insurer jointly and severally liable for mis-selling a policy to an elderly customer. When the bank and the insurer share liability, each needs a record of who sold the policy and what was explained.
Missing seller records, one-sided clawbacks and shared liability all point to the same gap: a credit record per policy.
How to prepare before the final rules
Five steps can begin now, before the consultation closes.
List every person who receives incentive credit on a bancassurance policy, at the bank and at the insurer.
Write the credit rule for each role, and record it on the policy at the time of sale.
Agree with each insurer partner how persistency, cancellation and complaint data will flow back to the bank, tagged to the seller.
Draft a clawback rule that reaches every person paid on a policy that cancels or is found mis-sold.
Model the cost and effect of moving bank staff from volume measures to quality measures, before the final rules set a deadline.
A credit record per policy, with data flowing back from the insurer, is the groundwork for whatever the final rules require.
How Kennect supports bancassurance incentives
Across the BFSI deployments we run, incentive disputes trace back to the record behind each sale. So we build the incentive cycle around that record.
We hold the credit rule for each role, at the bank or the insurer, as part of the plan. We bring in policy, renewal and cancellation data from the systems that already hold it. We calculate each person's incentive on the measures the plan names, and reverse credit on a policy that cancels, with the reason shown.
Finance sees the incentive accrued against each policy. Distribution heads see credit by seller, by branch and by insurer partner. Each seller sees the policies credited to them and the measures that drove their payout.
One record per policy, carrying every credit and every reversal, is what a policy-level seller tag will ask of a bancassurance incentive.
What this means for bancassurance heads
The consultation closes on 25 October 2026. Whatever the final rules say about permitted measures, they are likely to expect every policy to be tied to a seller and every mis-sold policy to carry a consequence. Banks and insurers that build that record now will adapt their schemes with less disruption when the rules are final.
A credit record per policy, with data flowing back from the insurer, is the groundwork for whatever the final rules require.
IRDAI has proposed tagging every policy to its seller and moving bank staff incentives away from volume. Both depend on knowing who gets credit for each policy.
See how incentive compensation management holds credit, measures and clawbacks on one record per policy.
Bank staff are paid by the bank, usually through branch or individual targets funded by the commission the insurer pays the bank as corporate agent. IRDAI's consultation paper of 23 September 2026 proposes prohibiting volume-linked or reward-linked incentives for bank and NBFC staff selling insurance.
The consultation paper proposes commission caps for distribution entities, a central identity mechanism tagging every policy to its seller, clawback where mis-selling is established, a ban on compulsory bundling and lower expense limits. Comments close on 25 October 2026, with reported implementation from FY2028.
Credit can sit with branch staff, the bank's insurance specialist, the insurer's relationship manager and the branch manager. The shares should be written into each plan before the sale and recorded on the policy, so every payout agrees with one record of who sold it.
Planning options include 13th-month persistency, free-look cancellations, completed suitability records, complaints and certification status, each tagged to the seller. Which measures are permitted depends on the final IRDAI rules, so take legal advice before redesigning any scheme.
In August 2026, a Hyderabad district consumer commission held a bank and an insurer jointly and severally liable for mis-selling a policy to an elderly customer. The ruling rejected the bank's argument that the sale was between the customer and the insurer alone.